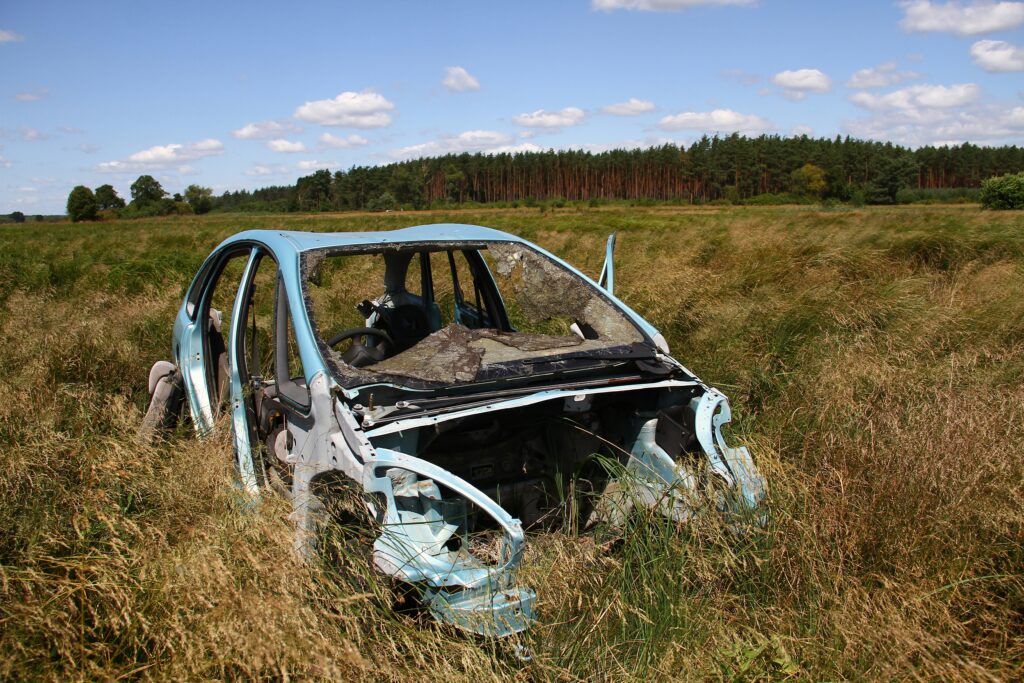
Picture two hypothetical drivers rear-ended at similar speeds on the same afternoon. Both cars need body work, both drivers feel sore, and both file claims. A few months later, one has a settlement check while the other is still waiting for answers.
That gap can feel unfair, especially when the accidents looked so alike. But insurance claims rarely move on a fixed schedule. Small differences in evidence, injuries, and paperwork can push two similar cases onto very different tracks. The calendar alone rarely tells the whole story.
People ask how long State Farm takes to settle a claim, and the honest answer is that it depends. The facts of the crash, the coverage involved, and the medical picture all shape the timeline, sometimes in ways nobody sees coming.
Why the Accident Itself Is Only Part of the Story
Fault is often the first hurdle. If both drivers blame each other, or the police report leaves questions open, the insurer may need more time to investigate. A clear-cut rear-end collision usually moves faster than a disputed intersection crash.
Evidence matters too. Photos, witness statements, dashcam footage, and repair estimates help an adjuster evaluate the claim. When key evidence is missing or contested, the review tends to slow down while everyone tries to fill in the gaps.
Policy coverage and the number of parties add more variables. Low policy limits, coverage questions, or multiple vehicles and insurers can complicate negotiations. Each additional party brings its own adjuster, its own position, and often its own timeline.
The Medical Factor That Can Change Everything
Injuries are often the biggest wild card. A driver who recovers in a few weeks may be ready to settle quickly. Someone still in treatment months later can’t easily put a value on a claim when the full cost of care isn’t known yet.
Future medical expenses add another layer of uncertainty. Surgery recommendations, physical therapy, or long-term care needs can significantly affect what a claim is worth, and estimating those costs often requires input from doctors and specialists. Insurers generally want those numbers documented before they commit.
Documentation gaps slow things down too. Missing records, delayed bills, or treatment that isn’t clearly connected to the accident can lead to requests for more information. Complete, organized medical documentation usually helps a claim move with fewer interruptions.
What Happens Inside an Insurance Company Before an Offer Is Made?
Once a claim comes in, an adjuster typically investigates. That can include reviewing the police report, talking with drivers and witnesses, inspecting vehicle damage, and requesting records. Each step takes time, especially when information has to come from outside sources.
Next comes evaluation. The adjuster reviews medical bills, treatment records, lost income documentation, and property damage to estimate what the claim may be worth. Insurers often rely on internal guidelines and software to help shape those assessments.
Settlement authority is another factor. Adjusters may only be able to approve offers up to a certain amount, and larger claims can require sign-off from supervisors. That internal approval process can add days or weeks before an offer arrives.
Why a Quick Settlement Isn’t Always a Better Settlement
A fast check can be tempting, especially when bills are piling up. But settling before the full extent of an injury is known can be risky. Once a settlement is accepted, reopening the claim for new problems generally isn’t an option.
That’s why some claims take longer for good reasons. Waiting for a clearer medical picture, gathering complete records, or getting expert opinions can help the final number reflect the true impact of the accident rather than an early guess.
Not every delay is legitimate, though. Unexplained silence, repeated requests for the same documents, or slow responses can sometimes signal stalling. Telling the difference between necessary steps and unreasonable delay often requires a closer look at the specific claim.
Conclusion
Two crashes can look almost identical and still follow very different paths to resolution. Fault disputes, evidence, coverage, the number of parties, and especially medical treatment all influence how long a claim takes to settle. No single factor decides it on its own.
Realistic expectations help. Some claims wrap up in weeks, while others take many months, and neither timeline guarantees a particular outcome. Keeping thorough records of medical care, expenses, and communications makes the process smoother for everyone involved.
Deadlines matter too. Texas generally gives injured people two years to file a personal injury lawsuit, though exceptions exist. A qualified attorney can explain the deadlines and options that apply, so a long wait doesn’t quietly turn into a missed opportunity.
 Ask Amy Glazerela how they got into market analysis and reports and you'll probably get a longer answer than you expected. The short version: Amy started doing it, got genuinely hooked, and at some point realized they had accumulated enough hard-won knowledge that it would be a waste not to share it. So they started writing.
What makes Amy worth reading is that they skips the obvious stuff. Nobody needs another surface-level take on Market Analysis and Reports, Investment Strategies and Trends, Wealth Management Strategies. What readers actually want is the nuance — the part that only becomes clear after you've made a few mistakes and figured out why. That's the territory Amy operates in. The writing is direct, occasionally blunt, and always built around what's actually true rather than what sounds good in an article. They has little patience for filler, which means they's pieces tend to be denser with real information than the average post on the same subject.
Amy doesn't write to impress anyone. They writes because they has things to say that they genuinely thinks people should hear. That motivation — basic as it sounds — produces something noticeably different from content written for clicks or word count. Readers pick up on it. The comments on Amy's work tend to reflect that.